Welche Finanzprodukte gibt es überhaupt?

Understanding the various types of financial products available is a fundamental step toward effective money management and achieving financial goals. These tools are designed to help individuals and businesses save, invest, borrow, and protect their assets. From simple savings accounts to complex investment vehicles, the landscape of Finanzprodukte can seem vast, but categorizing them helps in comprehending their purpose and utility in building a stable financial future. Whether you are planning for retirement, saving for a down payment, or seeking protection against unforeseen events, there is likely a financial product tailored to your specific needs.

Overview

  • Finanzprodukte encompass a wide range of tools for managing money and assets.
  • Investment products like stocks, bonds, mutual funds, and ETFs aim for capital growth.
  • Savings and deposit products offer secure places for funds, often with interest.
  • Insurance products provide financial protection against various risks, from health to property.
  • Credit and lending products offer capital for immediate needs, with repayment terms.
  • These products are utilized by individuals, businesses, and governments to achieve financial objectives.
  • Understanding different product categories helps individuals make informed financial decisions.

Common Investment Finanzprodukte

Investment Finanzprodukte are designed to help individuals and institutions grow their capital over time, often by taking on some level of risk. Stocks, for instance, represent ownership in a company, offering potential for capital appreciation and dividends. Bonds, on the other hand, are debt instruments issued by governments or corporations; investors lend money in exchange for regular interest payments and the return of their principal. Mutual funds and Exchange-Traded Funds (ETFs) provide diversification by pooling money from multiple investors to buy a portfolio of stocks, bonds, or other assets. Real estate is another significant investment, where individuals purchase properties either for rental income or for appreciation in value. These products cater to different risk tolerances and financial timelines, making them essential for long-term wealth creation.

Savings and Deposit Finanzprodukte Explained

Savings and deposit Finanzprodukte are fundamental for short-term financial management and emergency funds. These products typically offer safety and liquidity, meaning your money is readily accessible. A standard savings account allows you to deposit money and earn a modest amount of interest, while certificates of deposit (CDs) offer a fixed interest rate for a predetermined period, often higher than a regular savings account, but with penalties for early withdrawal. Money market accounts combine some features of savings accounts and checking accounts, often providing higher interest rates than regular savings accounts, along with check-writing privileges. In the US, these accounts are widely available through banks and credit unions, providing secure places to store cash while earning a return. These options are ideal for those prioritizing capital preservation and easy access to their funds.

Understanding Insurance Finanzprodukte

Insurance Finanzprodukte are critical for managing financial risks and protecting against unforeseen events. Life insurance provides a financial payout to beneficiaries upon the policyholder’s death, offering security to dependents. Health insurance covers medical expenses, which can be substantial, helping to protect individuals and families from high healthcare costs. Property insurance, such
Welche Haushaltsplan Tipps sind hilfreich?

Creating a household budget might seem like a daunting task, but with the right strategies, it becomes a powerful tool for achieving financial stability and peace of mind. Many individuals grapple with managing their money effectively, often wondering how to make their income stretch further or save for future aspirations. Fortunately, practical Haushaltsplan Tipps can simplify this process, offering clear steps to take control of your finances, understand where your money goes, and make informed decisions about spending and saving. This article will break down helpful methods, from initial setup to long-term maintenance, ensuring you have the knowledge to build a robust financial plan.

Overview:

  • Start by clearly defining your financial goals, whether short-term or long-term.
  • Accurately track all income and expenses to gain a comprehensive understanding of your cash flow.
  • Categorize your spending to identify areas where you can adjust or reduce outlays.
  • Utilize modern budgeting tools, apps, or spreadsheets to streamline the tracking process.
  • Implement budgeting rules like the 50/30/20 method to allocate funds effectively.
  • Regularly review and adjust your budget to ensure it remains relevant to your changing financial situation.
  • Prioritize an emergency fund and strategize for debt repayment to build financial security.

Erste Schritte für effektive Haushaltsplan Tipps

The foundation of any successful budget lies in understanding your current financial landscape and setting clear objectives. The first of the Haushaltsplan Tipps involves listing all sources of income. This includes your regular salary, any freelance earnings, benefits, or other money flowing into your household. Be precise; accuracy here is paramount. Once your income is established, the next crucial step is to define your financial goals. Are you saving for a down payment on a house, planning a vacation, building an emergency fund, or trying to pay off debt? Specific goals provide motivation and direction for your budget. Without a target, it’s easy to drift financially. For example, a goal to save $10,000 for an emergency fund within two years gives you a concrete monthly savings target. Simultaneously, begin tracking every single expense. This might feel tedious initially, but it’s essential to identify spending patterns. Many people are surprised to learn how much they spend on seemingly small, everyday items. This initial tracking period, perhaps for a month, provides a realistic snapshot of where your money truly goes.

Praktische Haushaltsplan Tipps zur Ausgabenverwaltung

Once you have a clear picture of your income and spending, the next set of Haushaltsplan Tipps focuses on managing your outgoings more effectively. A popular strategy is to categorize your expenses. Group similar items together, such as housing (rent/mortgage, utilities), transportation (gas, public transport, car payments), food (groceries, dining out), entertainment, and personal care. This categorization helps in identifying areas where spending might be excessive. A widely adopted method is the 50/30/20 rule: 50% of your income goes towards needs (housing, utilities, groceries), 30% towards wants (dining out, entertainment, hobbies), and 20% towards savings and debt repayment. This framework offers a simple yet effective way to allocate funds. Additionally, look for opportunities to reduce

Wie kann ich im Alltag am besten sparen?

Saving money in everyday life can feel like a daunting task, especially with rising costs and economic uncertainties. However, adopting small, consistent habits can significantly impact your financial well-being over time. It’s not about drastic sacrifices, but rather making informed choices and being more aware of where your money goes. By implementing practical strategies, anyone can start building a stronger financial foundation, freeing up resources for future goals or unexpected events.

Overview

  • Implement a detailed budget and track all your expenses to gain clarity on your spending habits.
  • Prioritize reducing household costs through energy efficiency, meal planning, and reviewing subscriptions.
  • Adopt mindful consumption by opting for secondhand items, DIY solutions, and reducing waste.
  • Make informed purchasing decisions by comparison shopping and avoiding impulse buys.
  • Automate savings and focus on debt reduction to build a solid financial safety net.
  • Leverage community resources and free entertainment to cut down on discretionary spending.
  • Negotiate bills and regularly review financial services to ensure you’re getting the best value.

Smart Spending Habits for Sparen im Alltag

A foundational step toward effective Sparen im Alltag is understanding where your money goes. Begin by creating a realistic budget that allocates funds for necessities, savings, and discretionary spending. Tools like spreadsheets or budgeting apps can help you track every dollar. Many people find success with the 50/30/20 rule: 50% for needs, 30% for wants, and 20% for savings and debt repayment. Once you know your spending patterns, you can identify areas for reduction. Impulse purchases are notorious budget busters; try implementing a “24-hour rule” where you wait a day before buying non-essential items. This pause often reveals whether the purchase is truly needed. Furthermore, consistently compare prices before making significant purchases, whether it’s groceries or electronics. Online comparison sites and store apps are valuable resources, applicable in regions like the US and beyond, to ensure you’re always getting the best deal. Opting for cash for daily expenditures can also help curb spending, as the physical act of handing over money often feels more tangible than swiping a card.

Reducing Household Costs for Sparen im Alltag

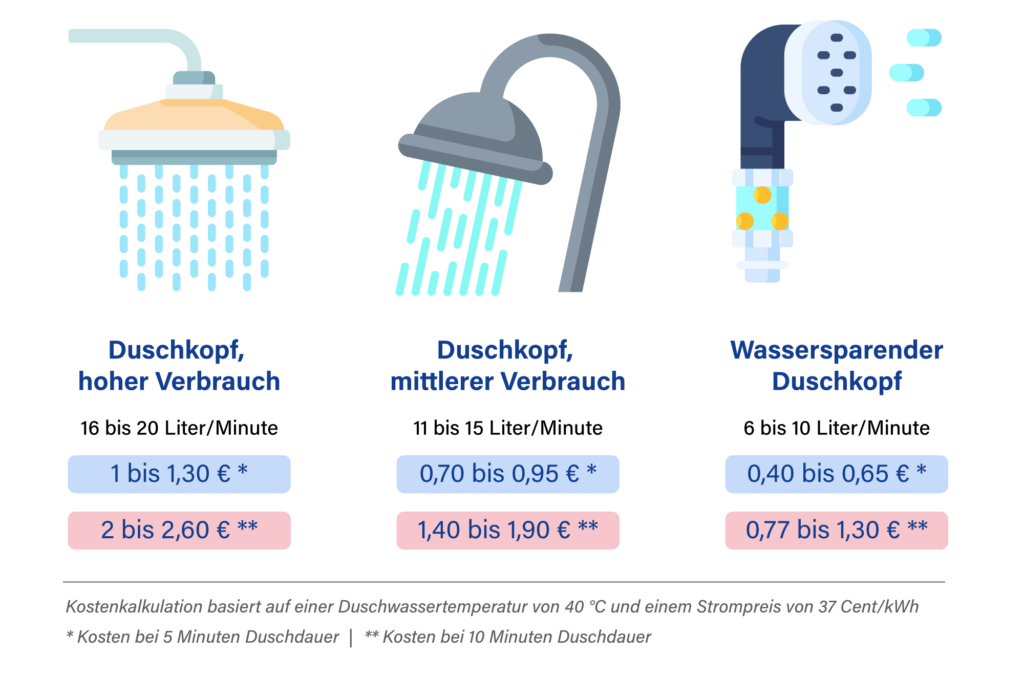
Household expenses represent a significant portion of most budgets, making them a prime target for Sparen im Alltag. Groceries are often one of the largest variable costs. Strategic meal planning, creating a shopping list, and sticking to it religiously can prevent overspending and food waste. Buying generic or store-brand products, which often offer comparable quality at a lower price, also adds up. When it comes to utilities, simple adjustments can yield substantial savings. Switching to LED light bulbs, unplugging electronics when not in use (phantom load), and adjusting your thermostat by a few degrees can noticeably lower electricity bills. Similarly, conserving water by taking shorter showers and fixing leaky faucets contributes to savings. Regularly review your subscription services – streaming platforms, gym memberships, or apps – and cancel any that you rarely use. For transportation, consider carpooling, utilizing public transit, walking, or biking for shorter distances. Regular vehicle maintenance can also improve

Empowering Finances: Insights for Financial Literacy

Empowering Finances: Insights for Financial Literacy

Empowering Finances: Navigating Financial Literacy Insights

Financial literacy is a cornerstone of personal and economic well-being, yet many individuals face challenges in understanding and managing their finances effectively. In this exploration, we unravel key insights that empower individuals to enhance their financial literacy and make informed decisions.

1. The Importance of Financial Education: A Foundation for Success

Financial education lays the foundation for informed decision-making. Understanding fundamental concepts such as budgeting, saving, investing, and debt management is crucial for navigating the complexities of personal finance. Investing time in financial education equips individuals with the knowledge needed to build a solid financial future.

2. Budgeting Basics: Mastering the Art of Money Management

Budgeting is a fundamental skill in financial literacy. Creating a budget helps individuals allocate their income wisely, prioritize expenses, and avoid unnecessary debt. Learning to track income and expenses allows for better control over financial resources, leading to increased financial stability and goal achievement.

3. The Power of Saving: Building a Financial Safety Net

Saving is a cornerstone of financial well-being. Whether for emergencies, future goals, or retirement, cultivating a savings habit is essential. Financial literacy insights emphasize the importance of setting aside a portion of income regularly. This practice not only provides a safety net but also opens doors to future opportunities and financial growth.

4. Investing Strategies: Growing Wealth for the Future

Understanding the basics of investing is key to building wealth over time. Financial literacy insights delve into various investment options, risk tolerance, and the power of compound interest. From stocks and bonds to real estate and retirement accounts, informed investment decisions contribute to long-term financial success.

5. Debt Management: Navigating the Borrowing Landscape

Debt can be a double-edged sword, offering financial flexibility but also posing risks. Financial literacy insights shed light on responsible borrowing, managing debt effectively, and understanding interest rates. Empowered with this knowledge, individuals can make informed decisions to avoid excessive debt and work towards financial freedom.

6. Credit Scores and Reports: Unlocking Financial Opportunities

Credit scores play a pivotal role in financial transactions, from securing loans to renting an apartment. Financial literacy insights delve into the factors influencing credit scores and the importance of maintaining a positive credit history. Understanding credit reports empowers individuals to improve their creditworthiness and access favorable financial opportunities.

7. Financial Goal Setting: Charting a Path to Success

Setting clear financial goals is a fundamental aspect of financial literacy. Insights in this area guide individuals in defining specific, measurable, achievable, relevant, and time-bound (SMART) financial objectives. Goal setting provides a roadmap for financial decision-making, ensuring that actions align with overarching aspirations.

8. Emergency Preparedness: Safeguarding Financial Stability

Unexpected events can have a significant impact on financial stability. Financial literacy insights emphasize the importance of emergency preparedness. Building an emergency fund, having insurance coverage, and understanding financial contingencies contribute to resilience in the face of unforeseen circumstances.

9. Tax Literacy: Navigating the Tax Landscape

Taxes are an inevitable aspect of financial life. Financial literacy insights delve into tax planning,